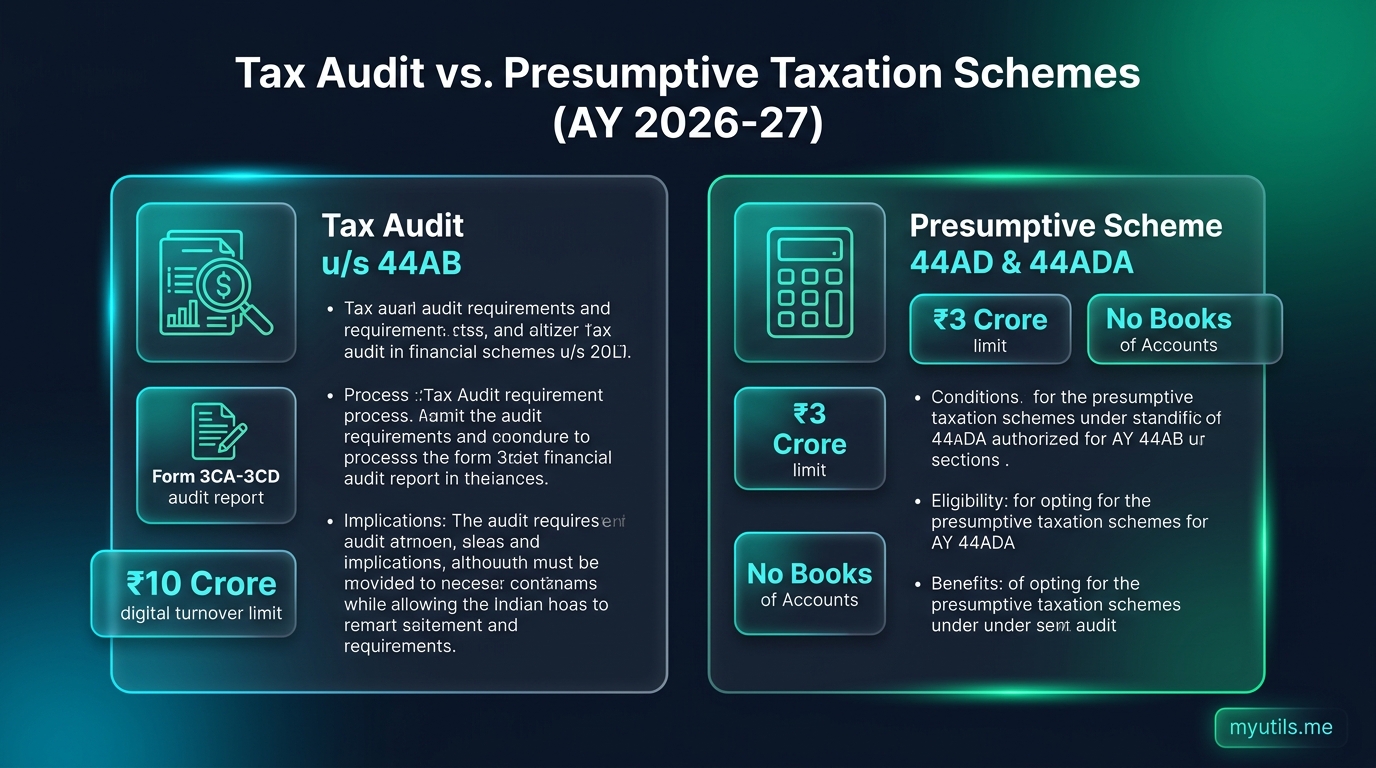
For small business owners, freelancers, software consultants, and practicing professionals in India, navigating the boundary between Presumptive Taxation and a Mandatory Tax Audit is one of the most consequential decisions of the financial year.
Opting for presumptive taxation under Section 44AD or Section 44ADA relieves you from maintaining tedious accounting books, recording daily expenses, and undergoing a formal audit by a Chartered Accountant.
On the other hand, miscalculating your cash transaction ratios or declaring profits lower than the prescribed percentages can trigger a mandatory Tax Audit under Section 44AB, accompanied by steep penalties under Section 271B if missed.
For Assessment Year 2026-27 (Financial Year 2025-26), the government has further expanded digital transaction thresholds:
- Business turnover under Section 44AD is eligible up to ₹3 Crore (with 95% digital receipts).
- Professional receipts under Section 44ADA are eligible up to ₹75 Lakh (with 95% digital receipts).
- General business tax audit threshold stands at ₹10 Crore for predominantly digital businesses.
Here is everything you need to know to stay completely compliant in AY 2026-27.

Thresholds & Applicability at a Glance (AY 2026-27)
| Section | Target Group | Turnover / Receipts Limit | Deemed Profit Rate | Audit Requirement |
|---|---|---|---|---|
| Section 44AD | Small Businesses (Retail, Wholesale, Manufacturing, Services) | ₹2 Crore (Cash)<br>₹3 Crore (≥95% Digital) | 6% on digital turnover<br>8% on cash turnover | Exempt from books & audit |
| Section 44ADA | Specified Professionals (Doctors, Engineers, Lawyers, CAs, Tech Consultants) | ₹50 Lakh (Cash)<br>₹75 Lakh (≥95% Digital) | 50% of gross receipts | Exempt from books & audit |
| Section 44AB | Any Business exceeding turnover limits | ₹1 Crore (Base limit)<br>₹10 Crore (≥95% Digital) | Actual audited net profit / loss | Mandatory audit by a CA (Form 3CA/3CB-3CD) |
| Section 44AB | Any Professional exceeding receipts limit | ₹50 Lakh (Base limit)<br>₹75 Lakh (if opting out of 44ADA) | Actual audited net profit / loss | Mandatory audit by a CA |

1. Section 44AD: Presumptive Scheme for Businesses
Who Can Opt In?
Resident Individuals, Hindu Undivided Families (HUFs), and Partnership Firms (excluding Limited Liability Partnerships / LLPs).
Who Is Excluded?
- Limited Liability Partnerships (LLPs) and Private Limited Companies.
- Individuals earning income from commission, brokerage, or agency business.
- Businesses engaged in the plying, hiring, or leasing of goods carriages (covered separately under Section 44AE).
Deemed Profit Rate: 6% vs 8%
Under Section 44AD, you do not need to calculate real expenses, depreciation, or utility bills. The law presumes your taxable income to be:
- 6% of total turnover: For all sales consideration received through banking channels (NEFT, RTGS, IMPS, UPI, debit/credit cards, or account payee cheques) on or before the return filing due date.
- 8% of total turnover: For any portion of turnover received in cash.
The Enhanced ₹3 Crore Limit Rule
The standard turnover cap for Section 44AD is ₹2 Crore. However, if aggregate cash receipts during the financial year do not exceed 5% of total turnover, the eligibility ceiling rises to ₹3 Crore.
The 5-Year Lock-In Trap (Section 44AD(4))
Many business owners fall into the dangerous Section 44AD(4) trap:
- If you opt into Section 44AD for one year, but in any of the subsequent 5 consecutive years you decide to declare profits lower than 6%/8%, you are barred from opting into Section 44AD for the next 5 assessment years.
- Furthermore, for that year and subsequent years, you are legally compelled to maintain books of accounts under Section 44AA and undergo a mandatory tax audit under Section 44AB (provided your total income exceeds the basic exemption limit).
Tired of Logging into the Tax Portal for Every Single PAN?
Track all your client and family ITR refund statuses, intimation notices, and AIS summaries from one clean, automated dashboard.
2. Section 44ADA: Presumptive Scheme for Professionals
Who Qualifies as a "Specified Professional"?
Section 44ADA applies exclusively to resident individuals and partnership firms (excluding LLPs) engaged in:
- Legal, Medical, Engineering, or Architectural professions.
- Accountancy (Chartered Accountants).
- Technical Consultancy & Software Development / IT Consulting.
- Interior Decoration.
- Authorized Representatives & Company Secretaries.
- Film Artists, Directors, and Designers.
How Does the 50% Profit Rule Work?
- Under Section 44ADA, 50% of your gross professional receipts are presumed to be your taxable net profit.
- The remaining 50% is treated as having absorbed all your professional expenses: office rent, laptop depreciation, internet bills, client entertainment, and travel.
- Example: A freelance software developer receives ₹60 Lakhs entirely via bank transfers. Under Section 44ADA, their taxable income is simply ₹30 Lakhs (50%). No expense receipts, rent agreements, or invoices need to be preserved for the tax department.
Enhanced ₹75 Lakh Threshold
While the baseline cap is ₹50 Lakh, if your cash receipts do not exceed 5% of gross receipts, you can utilize Section 44ADA for total annual billings up to ₹75 Lakh.
What If Your Actual Profit Is Below 50%?
If your actual profit margin is only 30% and you wish to declare lower income:
- You cannot use the simplified ITR-4 form.
- You must file ITR-3, maintain formal books of accounts under Section 44AA, and undergo a Tax Audit under Section 44AB by a Chartered Accountant (if your total income exceeds the basic exemption limit).
3. Section 44AB: When Is a Full Tax Audit Mandatory?
A Tax Audit under Section 44AB requires a practicing Chartered Accountant to audit your books of accounts, verify statutory deductions, inspect TDS compliance, and upload Form 3CA-3CD or Form 3CB-3CD on the e-filing portal.
Triggers for Section 44AB in AY 2026-27
| Trigger Condition | Scenario | Statutory Rule |
|---|---|---|
| 1. Business Turnover > ₹1 Crore | Cash transactions exceed 5% | Tax audit mandatory under Section 44AB(a). |
| 2. Business Turnover > ₹10 Crore | Digital receipts and payments ≥ 95% | Tax audit mandatory under Section 44AB(a) proviso. |
| 3. Professional Receipts > ₹50 Lakh | Cash receipts exceed 5% | Tax audit mandatory under Section 44AB(b). |
| 4. Professional Receipts > ₹75 Lakh | Digital receipts ≥ 95% | Tax audit mandatory if receipts cross ₹75L. |
| 5. Deemed Profits Lower than Prescribed | Profits declared below 6%/8% (44AD) or 50% (44ADA) | Tax audit mandatory to substantiate lower margin. |
| 6. 44AD 5-Year Lock-In Breach | Opted out of Section 44AD within 5-year block | Mandatory audit for next 5 consecutive years. |
Statutory Due Date for Tax Audit
- The Tax Audit Report (Form 3CA-CD / 3CB-CD) must be submitted electronically by the CA on or before September 30 of the Assessment Year.
- The taxpayer’s corresponding ITR-3 / ITR-5 return must then be e-filed on or before October 31.
Penalty for Failure to Get Accounts Audited (Section 271B)
Failing to complete your tax audit or missing the September 30 deadline attracts a severe monetary penalty under Section 271B:
- 0.5% of total turnover / gross receipts, or
- ₹1,50,000, whichever is lower.
Summary Decision Matrix: Which Route Should You Choose?
| Category | Turnover / Gross Receipts | Declared Margin | Applicable Compliance Route |
|---|---|---|---|
| Professionals | Up to ₹75 Lakh (≥ 95% digital) | ≥ 50% of gross receipts | File ITR-4 u/s 44ADA (Exempt from books and audit) |
| Professionals | Up to ₹75 Lakh | Less than 50% of receipts | File ITR-3 + CA Tax Audit u/s 44AB |
| Professionals | Exceeding ₹75 Lakh | Any margin | Mandatory Tax Audit u/s 44AB |
| Small Businesses | Up to ₹3 Crore (≥ 95% digital) | ≥ 6% (digital) / 8% (cash) | File ITR-4 u/s 44AD (Exempt from books and audit) |
| Small Businesses | Up to ₹3 Crore | Less than 6% / 8% | File ITR-3 + CA Tax Audit u/s 44AB |
| Mid-Sized Businesses | ₹3 Crore to ₹10 Crore (≥ 95% digital) | Normal commercial profit | Maintain Books, Audit Exempt u/s 44AB |
| All Businesses | Exceeds ₹1 Cr (cash > 5%) or ₹10 Cr | Any margin | Mandatory Tax Audit u/s 44AB |
Key Takeaways
- Maximize Digital Receipts: Keeping your physical cash receipts below 5% of turnover unlocks the elevated ₹3 Crore limit for 44AD, ₹75 Lakh for 44ADA, and ₹10 Crore for Section 44AB audits.
- Beware the 44AD 5-Year Trap: Do not jump out of 44AD lightly; walking away from the 6%/8% presumptive margin triggers a 5-year exclusion and forces mandatory audits.
- Reconcile with AIS SFT Data: Whether you claim presumptive status or complete a tax audit, CPC cross-references your reported turnover against SFT codes and Form 26AS.
- Multi-Client Practice Automation: Chartered Accountants managing dozens of audit and presumptive clients can monitor audit readiness, turnover thresholds, and filing timelines using centralized practice dashboards like myutils.me.

myutils.me
Tax Compliance Research Team
Official editorial and compliance research team at myutils.me, building automated tools for income tax return tracking, AIS/TIS reconciliation, and direct tax workflows.